About Us
Independent advisors committed to protecting your assets and helping you build lasting wealth with trusted guidance.

Who we are
At Safe Pacific, we craft personalized financial plans for success-driven Canadians, empowering them to use life insurance as a strategic financial tool. By protecting their greatest assets and helping them achieve lasting financial security, we give our clients peace of mind. We always act in their best interest—because their success is our mission, and their trust is why we love what we do.
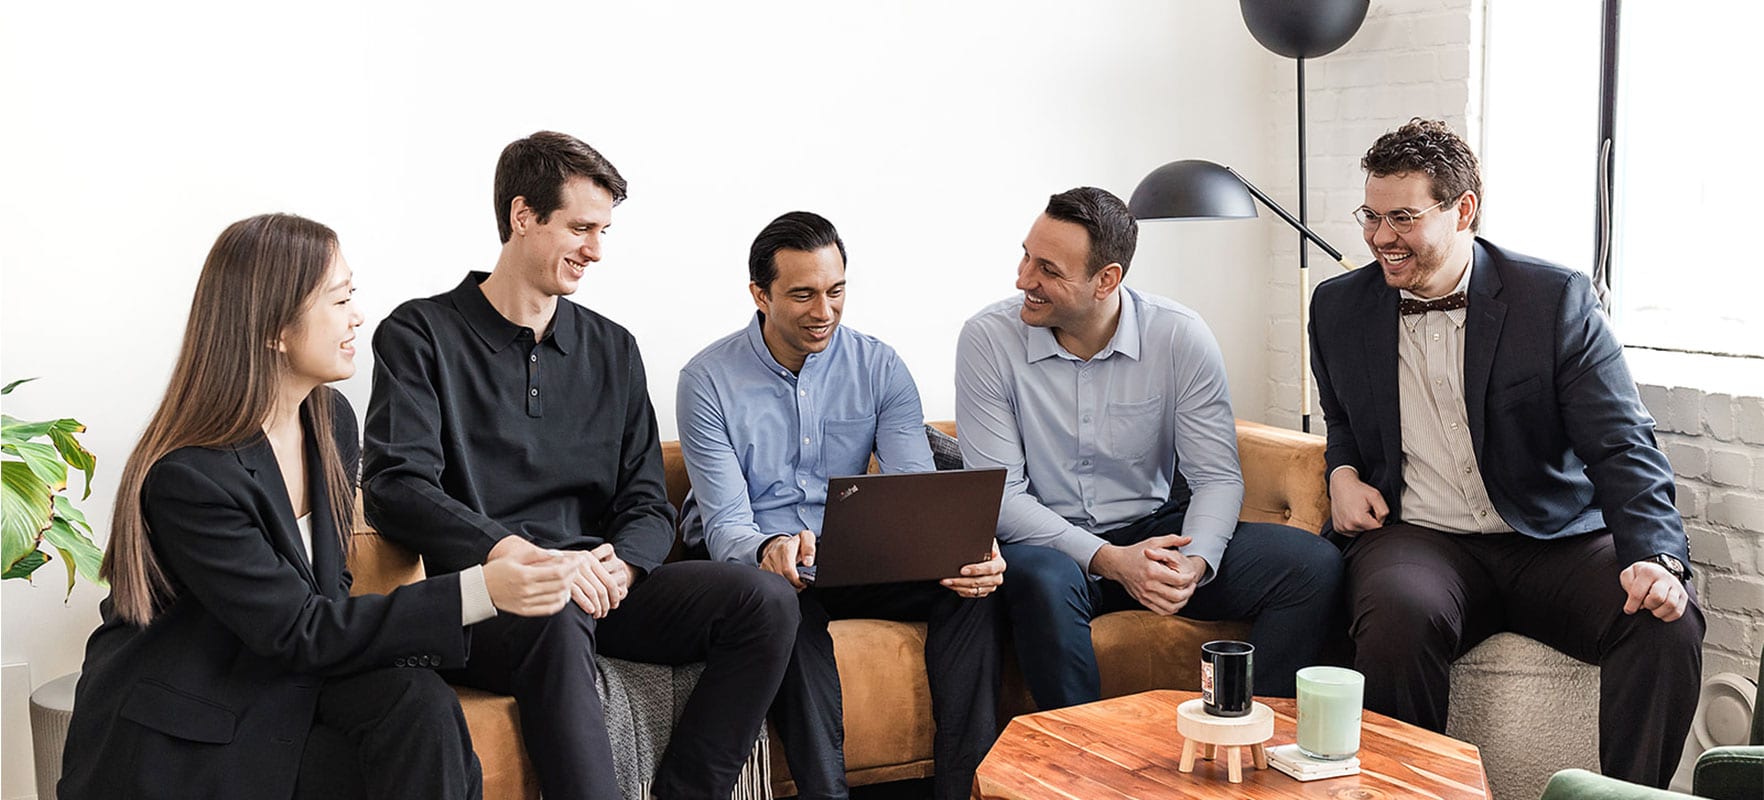
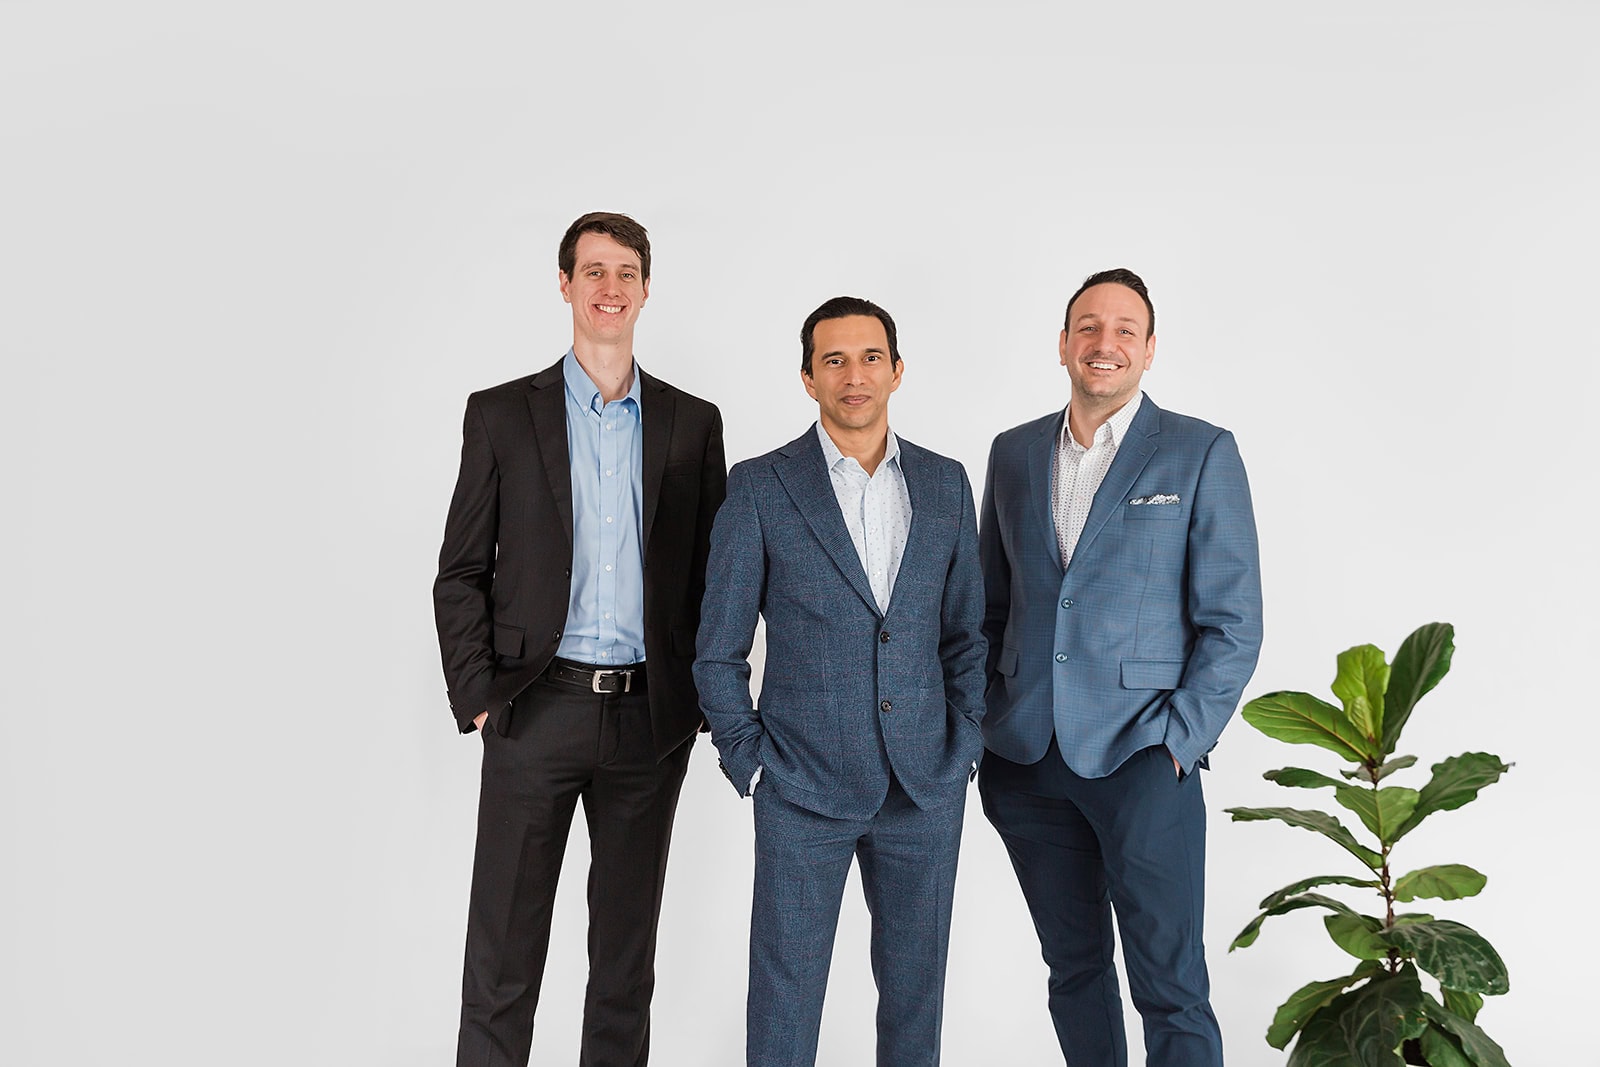
The Safe Pacific Team
Safe Pacific’s dedicated, independent team of experts puts clients first, offering trusted, personalized financial guidance.



Check out our latest insights
Thoughts and insights, updated weekly.
Your Plan Is Only as Good as the Numbers Behind It
Executive Summary A financial plan built on estimates can look perfectly reasonable and still point you in the wrong direction, because small errors in ownership,...
Infinite Banking: The Truth Behind the Hype
Executive Summary The mechanics of infinite banking are completely real, borrowing against the cash value of a participating whole life policy is a legitimate strategy...
The Trapped-Cash Problem
Executive Summary Surplus profit sitting in a corporate bank or investment account is quietly taxed twice, once on the investment income at close to 50%...
Right-Sizing: Why the Best Strategy Isn't Always the Biggest or the Smallest One
Executive Summary The right strategy is the one correctly sized to what you're actually trying to accomplish, which sometimes means less than what's on the...

The Corporate Asset Your Accountant Isn't Talking About
Executive Summary A properly structured corporate-owned participating whole life policy functions less like insurance and more like a tax-sheltered fixed-income allocation on your corporate balance...
If Something Happened to You Tomorrow… Would Your Plan Actually Work?
Executive Summary: Probably not the way you think, because most business owners have the components of a plan rather than a plan designed to function...
You’re Not Paying Too Much Tax — You Just Don’t Have a Strategy
Executive Summary The tax bill that frustrates incorporated Canadians usually isn't caused by the rates, it's caused by the absence of a coordinated strategy across...
The Silent Risk in Your Portfolio
Executive Summary The silent risk is real estate concentration, where 60% to 80% of a successful Canadian's net worth sits in property that can't be...
Why High Income Isn't the Same as Financial Security
Executive Summary A high income is a resource, not a financial plan, and on its own it can hide real structural fragility behind lifestyle creep,...
Your Corporation Has Accounts You've Probably Never Seen
Executive Summary Your corporation tracks three notional accounts, the Capital Dividend Account, RDTOH, and GRIP, that never appear on a statement but directly determine how...
What Happens After You Reach Out to Safe Pacific?
Executive Summary When you reach out to Safe Pacific, a real person from our team emails you within 24 hours with a link to book...
The Protection Playbook for High-Income Employees
Here's something that surprises a lot of people. Some of the most financially fragile households we see are actually very high-income families. Not because they're...
Let's Get Social
See more about life at Safe Pacific and watch our myriad videos on Instagram and Youtube.


Critical illness insurance is designed to protect you financially when a serious diagnosis affects your ability to work, run your business, or maintain your lifestyle.
Most plans cover around 25 conditions, including cancer, heart attack, stroke, coronary bypass surgery, organ transplants, kidney failure, MS, Parkinson’s, ALS, Alzheimer’s, severe burns, and paralysis. Some carriers add more, like occupational HIV coverage we often set up for doctors and nurses.
But about 80% of claims come from just four: cancer, stroke, heart attack, and coronary bypass surgery.
Comment "MEETING" to book a free consultation.


Without proper estate planning, your estate becomes vulnerable to complications that are entirely avoidable.
Probate can take months or years, makes your financial affairs public record, delays your beneficiaries` access to funds, and comes with fees depending on your province. Your corporate shares, investments, and appreciated real estate can trigger a deemed disposition, leaving your heirs a capital gains bill they may have to sell assets to pay.
Add unclear intentions, and you get family disputes on top of it.
Comment "MEETING" to book a free call.
Three details that separate a good disability policy from a great one.
ㅤ
Partial and residual coverage, so if you go back to work part-time, you still get benefits topping up your lost income. A benefit period to age 65, not just two or five years. And the right to use your own doctor when you claim, instead of proving you’re sick to someone you’ve never met.
ㅤ
Not every plan includes these. Mark’s does.
ㅤ
Comment "MEETING" to book a free call.
Critical illness policies cover somewhere between 22 and 26 named illnesses depending on the carrier. Cancer, stroke, heart attack, and more.
And with almost every one of them, the first thing your doctor tells you is to reduce stress while you recover.
So what`s one of the biggest stressors for Canadians? Money. A tax-free lump sum takes that off the table so you can focus on getting better.
Comment "MEETING" to book a free call.
Cancer. Stroke. Heart attack. Survive the diagnosis and critical illness insurance pays you a tax-free lump sum, no receipts required.
It`s not health insurance reimbursing your bills. It`s not disability replacing your paycheck. It`s cash you can use however you want.
Cover the mortgage while you heal. Fly out of country for a specialist. Hire a caregiver. Pay for private rehab or home modifications. Your call.
Comment "MEETING" to book a free call.
Today we pause to honour the Canadians who served, and those who continue to serve, so that we can live in peace. We`ll be back in the office tomorrow.
Can you protect your income when money is already tight?
ㅤ
That was Mark’s challenge. He had $100 to $300 a month to put toward insurance, about $100,000 in student debt, and very little emergency savings. Every dollar early in his physio practice already had a job.
ㅤ
Without a financial cushion, one unexpected injury or illness could wipe out everything he’d built. That’s exactly why the right disability policy mattered so much.
ㅤ
Comment "MEETING" to book a free call.
$100,000 in student debt. A brand new practice. No spouse, no second income, no backup.
ㅤ
That was Mark, a 35-year-old self-employed physiotherapist who just made a major career change. He was doing everything right, paying down loans, building his practice, investing on his own.
ㅤ
But his hands, mobility, and strength are his livelihood. One injury or illness and his income stops, his debt payments fall behind, and his second career unravels.
ㅤ
Comment "MEETING" to book a free call.
Here’s a simplified version of a real client situation.
A Canadian business owner with a holding company and an operating company has built up about $2 million in unrealized capital gains from commercial real estate and a corporate investment portfolio.
When they pass away, the CRA treats those assets as sold at fair market value. Half the $2 million gain is taxable, and at a 50% marginal rate, that’s a $500,000 tax bill due on death.
Comment "MEETING" to book a free call.
Life insurance is often used alongside advanced post-mortem tax strategies.
Loss carryback planning uses losses triggered at death to offset capital gains on your final return. Pipeline planning converts corporate retained earnings into capital gains instead of taxable dividends. An estate freeze locks in today’s value and passes future growth to your family.
Permanent insurance makes all three easier and more reliable, because the CRA wants its money on the next tax filing, and your family receives nothing until it’s paid.
Comment "MEETING" to book a free call.
How much disability insurance do you actually need? It`s the question we get most.
The short answer: as much as you can qualify for. Coverage is capped by your income, usually 60% to 80% of what you earn, and it`s designed to replace your after-tax income.
At minimum, you need enough to maintain your lifestyle and keep paying your obligations if your income stopped tomorrow. Hospital for eight months. Bills still due.
Comment "MEETING" to book a free call.
$0 in personal tax. That`s what`s possible when a capital dividend is properly elected through your corporation`s Capital Dividend Account.
The CDA is a notional account, not a bank account, but it`s one of the most efficient ways to move life insurance proceeds and other tax-free gains out of a corporation and into your hands.
It has to be set up before you need it, not after. Comment “MEETING” and we`ll send you the link to talk through your structure in a free consultation.
Capital gains can take a major bite out of your estate, especially if you own real estate, private corporation shares, or other appreciating assets. But there’s a proven, CRA-compliant way to handle it.
Permanent life insurance, whether whole life, universal life, or term 100, pays a guaranteed tax-free death benefit to your beneficiaries or estate. That lump sum can cover the capital gains triggered when you pass.
Your family doesn’t have to sell property, liquidate investments, or give up business shares. The estate passes on intact.
Comment "MEETING" to book a free call.
What does the right coverage look like when your career depends on your body?
ㅤ
For Mark, a self-employed physiotherapist, it meant an occupation-specific disability policy that pays if he can’t do his job, even if he could do something else. It also meant adding a future income option rider so he can increase his coverage as his income grows, without reapplying or another medical exam.
ㅤ
With no dependents, life insurance could come later. Protecting his income came first.
ㅤ
Comment "MEETING" to book a free call.
Your executor settles your debts, files your final tax return, distributes your assets, and may have to manage or sell your business. It can take months or years.
So don`t assign it lightly. You need someone trustworthy, financially literate, impartial, and willing. Executors can decline the role, so get consent and name a backup in writing.
For complex estates, a professional executor can prevent family conflict and make probate go smoother.
Comment "MEETING" to book a free call.
One of our clients is a physiotherapist, and she told us she can tell exactly who has insurance.
When she recommends coming back every few days, the insured patients say no problem, I’ll be there. The ones without coverage ask how much it’ll cost and whether they can come every two weeks instead.
They’re negotiating on their recovery. For a hundred or a couple hundred dollars a month, critical illness insurance takes that stress away so you can focus on getting better.
Comment "MEETING" to book a free call.
Contact us
Let’s chat. Fill out this form and a member of our team will get back to you within 24hrs on business days.
"*" indicates required fields


